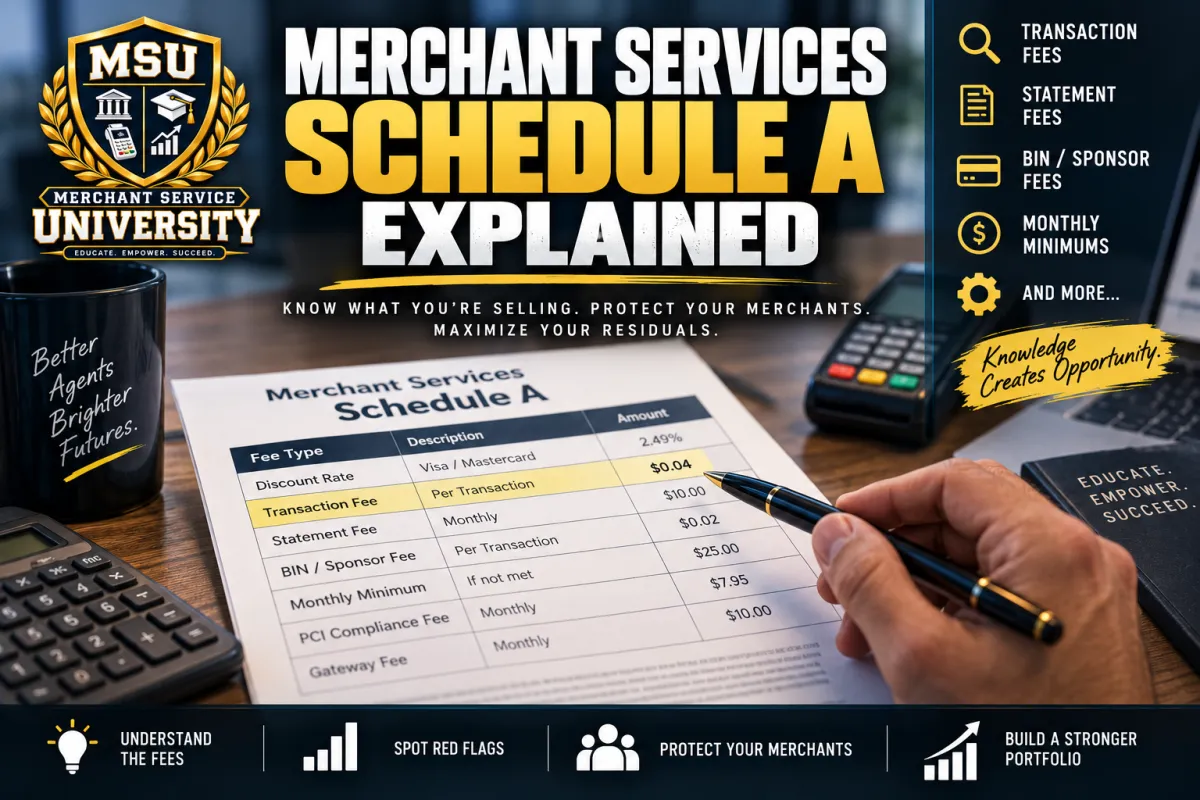
Merchant Services Schedule A Explained: Why Costs Matter
Merchant Services Schedule A Explained: Why Your Costs Matter as Much as Your Residual Split
A merchant services Schedule A doesn't need to be complicated.
At its core, it helps define some of the underlying costs associated with the merchants you place through an ISO or processor. Those costs matter because they can reduce the amount of profit available before your residual split is calculated.
This is one of the biggest things I wish new agents understood when comparing merchant services companies.
Someone tells you:
"We'll pay you 50%."
Another company tells you:
"We'll pay you 60%."
Naturally, 60% sounds better.
But it isn't automatically better.
If the company offering 60% has substantially higher costs underneath that split, you can actually make less money than you would with a strong 50% agreement.
That's what this article is about.
I'm not going to tell you to become an expert at comparing every single line item on five different Schedule A documents. I don't think most sales agents need to turn themselves into accountants.
What I do want you to understand is that Schedule A costs are not all created equal, and small differences can become significant once you multiply them across thousands of transactions and dozens or hundreds of merchants.
There is also nothing inherently wrong with having fees on a Schedule A. Every payment-processing relationship has costs somewhere. The question isn't whether costs exist.
The question is:
How much are they?
If you're still learning how residual compensation works, start with my guide to Merchant Services Agent Commissions. That will make the examples below much easier to understand.
What Is a Merchant Services Schedule A?
A Schedule A is generally a pricing or compensation schedule connected to your merchant-services agent agreement. It can identify underlying costs associated with the accounts you submit, such as transaction fees, monthly fees, authorization costs, statement fees, platform costs, BIN or sponsor expenses and other program-specific charges.
Different ISOs structure these schedules differently. The terminology can vary, and the specific costs can vary.
That's normal.
The important thing for an agent is understanding that these costs can come out before the remaining profit is divided according to your residual split.
A simplified way to think about it is:
Merchant Revenue − Applicable Costs = Remaining Eligible Profit
Then:
Remaining Eligible Profit × Your Residual Split = Your Residual
The exact calculation depends on your agreement, but this simple framework explains why your Schedule A matters.
A higher cost leaves less profit to divide.
A lower cost leaves more profit to divide.
That sounds obvious once you understand it, but I spent years in this industry before I fully appreciated how much some of these little numbers could affect an entire portfolio.
The Transaction Fee Example: How Two Cents Can Beat a Higher Split
This is probably the easiest example.
Imagine two companies are competing for your business.
Company A
Your Schedule A transaction cost is:
$0.04 per transaction
Your residual split is:
50%
Company B
Your Schedule A transaction cost is:
$0.06 per transaction
Your residual split is:
60%
At first glance, most agents are going to look at 50% versus 60% and assume Company B is better.
Now let's look at the transaction cost.
Suppose the merchant processes 5,000 transactions per month.
At four cents per transaction, Company A's transaction cost is:
5,000 × $0.04 = $200
At six cents per transaction, Company B's transaction cost is:
5,000 × $0.06 = $300
That's a $100 monthly difference in underlying cost from only two cents per transaction.
Now let's assume, purely for illustration, that there was $600 in account-level margin available before applying that particular transaction-fee cost.
With Company A:
$600 − $200 = $400 remaining
Your 50% share:
$400 × 50% = $200
With Company B:
$600 − $300 = $300 remaining
Your 60% share:
$300 × 60% = $180
The company offering the 60% residual split paid you $180.
The company offering the 50% residual split paid you $200.
That's the lesson.
The higher split still produced less money because the underlying cost was higher.
These numbers are only a hypothetical example, but the math demonstrates exactly why I don't get overly excited when someone tells me they offer a bigger residual percentage.
I want to know what the costs underneath it look like.
My First Schedule A Had a $0.10 Transaction Cost—and I Didn't Even Know
This is one of the reasons I'm passionate about teaching agents this early.
The first company I worked with had a transaction fee cost to me of around $0.10 per transaction.
At the time, I didn't really understand what that meant.
I was selling.
I was signing merchants.
I was building residuals.
But I wasn't looking underneath the economics closely enough.
Think about how big that number is compared with the example above.
At 5,000 transactions per month:
5,000 × $0.10 = $500 in transaction costs
If the merchant itself was only being charged around that amount per transaction, there wasn't much transaction-fee margin left for me to participate in.
I could have been selling accounts, creating revenue and believing I had a good split without realizing one of my underlying costs was eating up a major portion of the potential profit on every transaction.
That's why education matters.
I wasn't stupid.
I simply didn't know what I didn't know.
Today, if someone shows me a Schedule A, one of the first things I want to understand is what I'm being charged per transaction.
A few pennies can look meaningless.
Across thousands of transactions, they're not.
Statement Fees Can Work the Same Way
Statement fees are another good example because the individual difference may look tiny.
Suppose one Schedule A charges you:
$5 per merchant per month
and another charges:
$10 per merchant per month
That's only a $5 difference.
Who cares?
With one merchant, probably not much.
Now build a portfolio of 100 merchants.
That $5 difference becomes:
100 merchants × $5 = $500 per month
If those costs reduce the eligible profit before your 50% split, that $500 difference can represent approximately:
$250 per month in agent residual compensation
under that simplified example.
Now think annually:
$250 × 12 = $3,000
A five-dollar cost difference that seemed irrelevant on one account potentially became a $3,000 annual difference across the portfolio.
That's why small Schedule A costs become much more important as your book grows.
You don't need to obsess over every dollar when you're signing your first merchant.
You do need to understand that those dollars multiply.
A Higher Split Can Lose on the Statement Fee Too
Let's make the example even simpler.
Assume you charge the merchant a $15 monthly statement-related fee.
Company A has a $5 underlying statement cost.
That leaves:
$10 of margin
At a 50% residual split:
You receive $5
Company B has a $10 underlying statement cost.
That leaves:
$5 of margin
Even with a 60% residual split:
You receive $3
Once again:
50% produced more actual money than 60%.
Not because 50% is magically better.
Because the economics underneath it were better.
That is the entire lesson I want agents to understand.
What Is a BIN Fee or Sponsor Fee?
Depending on your processing relationship, you may also see costs associated with bank sponsorship, BIN relationships or similar monthly account expenses.
Don't get hung up on the terminology. Different companies may describe these fees differently.
Focus on what the cost does to your account economics.
Suppose Company A has a $5 monthly sponsor-related cost and Company B has a $10 cost.
That's another $5 difference per merchant.
Across 100 merchants:
$5 × 100 = $500 per month
Again, if that cost reduces the profit pool before a 50% split, the difference could affect the agent's side by approximately:
$250 per month
under a simplified revenue-sharing example.
None of this means a $10 BIN or sponsor fee is automatically bad.
Maybe the overall Schedule A is excellent.
Maybe the company offers better technology.
Maybe its transaction cost is lower.
Maybe its support is dramatically better.
Maybe the relationship creates better merchant retention.
You have to look at the overall economics.
The important thing is simply recognizing that these costs exist and affect what is left to divide.
Monthly Fees and Minimums Can Matter Even More When You Waive Them
This is an area I think agents especially need to understand.
You may have a monthly fee or monthly minimum built into your Schedule A.
Again, there is nothing inherently wrong with that.
But you need to know the cost is there before you start waiving fees for merchants.
Suppose your Schedule A contains a $10 monthly account cost.
You really want to close a merchant, so you tell them:
"I'll waive the monthly fee."
That's fine if you've intentionally chosen to give up that revenue.
The problem is when you think waiving the merchant's fee also eliminates the cost underneath it.
It may not.
Depending on your agreement, the underlying $10 cost can still exist.
Now instead of generating margin from the monthly fee, you've potentially created an expense that reduces the profitability of the account.
Do that on one merchant and you probably won't care.
Do it across 50 merchants:
50 × $10 = $500 per month in underlying costs
The lesson isn't:
Never waive fees.
I've waived plenty of fees to make deals work.
The lesson is:
Know what you're waiving.
If I know a particular merchant is going to generate tremendous processing revenue, I may willingly give away a monthly fee because it makes sense for the total relationship.
That's a business decision.
Making the same decision because I didn't realize the cost existed is very different.
There Is Nothing Wrong With Having Costs on a Schedule A
I want to make this extremely clear because I don't want agents reading this article and suddenly believing every fee represents an ISO trying to take advantage of them.
That's not the message.
Every business has costs.
Your ISO is providing infrastructure.
The processor is providing infrastructure.
There are banking relationships, technology, underwriting, support, risk, reporting and operational expenses throughout the payment ecosystem.
Someone has to pay for those things.
I expect my ISO to make money.
In fact, I want my ISO to make money because I want the organization supporting my merchants to be financially healthy and capable of providing excellent service.
The question is not:
"Does my Schedule A contain fees?"
The better question is:
"Are the costs reasonable, and do I understand how they affect my residual?"
That's it.
Why I Still Like a Clean 50% Split
This is one reason I'm comfortable offering and working around a clean 50% residual split.
I don't need someone promising 80% or 90% just so the number looks impressive.
If the underlying economics are good, a 50% relationship can produce excellent results.
If the transaction fees are competitive, monthly costs are reasonable, reporting is transparent, residual rights are protected and the ISO provides the backend infrastructure that lets me focus on selling, that can be a great partnership.
If production later justifies 55% or 60%, that's great too.
But the split should never be evaluated without understanding the cost structure underneath it.
That's why I tell agents:
Don't ask only what percentage you're getting. Ask what you're getting a percentage of.
You Don't Need to Compare Every Line Item—You Need to Understand the Big Ones
This is where I want to keep things practical.
I'm not telling a new merchant services salesperson to request six Schedule A documents and spend a week building spreadsheets comparing every possible cost.
Most agents don't need to do that.
I want you to understand enough that you don't sign blindly.
Look at the costs that can materially affect the merchants you're likely to sell.
If you're working with high-transaction businesses, the transaction fee matters tremendously.
If you're building hundreds of small merchants, fixed monthly costs can accumulate.
If there are monthly minimums, BIN fees, sponsor fees or statement costs, understand what they are.
Then ask someone to explain anything you don't recognize.
You're not trying to become a processing accountant.
You're trying to understand the basic economics of the portfolio you're building.
How the Schedule A Fits Into Your Agent Agreement
Your Schedule A should also be considered together with your merchant services agent agreement.
The Schedule A helps explain the economics.
The agreement helps explain the rules governing those economics.
Can costs change?
Can your residual split change?
Are residuals vested?
What happens if you stop producing?
What happens if you leave?
That's why I don't evaluate a merchant services company based only on compensation.
When I explained how to choose a merchant services agent program, I included Schedule A economics alongside the agreement, technology, merchant support, underwriting and residual rights.
They all work together.
A low-cost Schedule A attached to a terrible partnership isn't automatically a good deal.
A slightly higher cost structure attached to tremendous merchant support may be worth every penny.
You have to evaluate the complete relationship.
Want to Understand This Before Choosing a Merchant Services Company?
If terms such as Schedule A, transaction costs, residual split and eligible profit are still new to you, that's exactly why I believe education should come before recruitment.
You can access the core education inside Merchant Service University completely free.
The goal is to help you understand how merchant services works before somebody puts a compensation plan or agreement in front of you and asks you to make a long-term decision.
Inside MSU, you'll learn the fundamentals of payment processing, merchant pricing, statements, residual income, industry structure, modern commerce systems and merchant sales.
There is no charge for the core education and no obligation to join one specific merchant-services company.
Start Merchant Service University Free
https://merchantserviceuniversity.com
Learn what the numbers mean before you choose where you want to build.
Get educated before you get recruited.
Frequently Asked Questions About Merchant Services Schedule A Costs
What is a merchant services Schedule A?
A merchant services Schedule A is generally a pricing or compensation schedule associated with an agent agreement. It may contain underlying transaction costs, monthly fees, authorization expenses, sponsor or BIN-related fees and other costs that affect the profit available for residual sharing.
Why does a Schedule A matter to an agent?
Schedule A costs can reduce the amount of eligible profit remaining before the agent's residual percentage is applied. Two companies can offer different residual percentages and still produce very different actual payouts because their underlying costs differ.
Is a 60% residual split always better than a 50% split?
No. If the company offering 60% has substantially higher underlying costs, the smaller remaining profit pool can result in less actual agent compensation than a strong 50% agreement.
How much does a two-cent transaction-fee difference matter?
At 5,000 transactions per month, a two-cent difference represents $100 in monthly underlying cost. Across larger merchants or an entire portfolio, small per-transaction differences can become significant.
Why do statement fees matter?
A small difference in monthly statement cost may seem insignificant on one merchant but becomes larger across a portfolio. A $5 difference across 100 merchants represents $500 per month in underlying margin difference before residual sharing.
What is a BIN or sponsor fee?
Depending on the processing relationship, an agent Schedule A may include monthly costs related to bank sponsorship, BIN relationships or similar processing infrastructure. Terminology and amounts vary between organizations.
What happens if I waive a merchant's monthly fee?
Waiving the merchant-facing fee does not necessarily eliminate the underlying cost on your Schedule A. Depending on the agreement, the account can still incur that cost, reducing the merchant's profitability and potentially the agent's residual.
Are fees on a Schedule A bad?
No. Processing relationships naturally contain costs. The important issue is understanding what the costs are, whether they are reasonable and how they affect the residual economics of your merchant portfolio.
Is a 50% merchant services residual split good?
A clean 50% split can be a strong compensation structure when the underlying costs are competitive, residual rights are protected and the ISO provides valuable technology, operations and merchant support.
Where can I learn merchant services compensation for free?
You can learn foundational merchant-services concepts through Merchant Service University, including processing, pricing, statements, residual income and the economics agents should understand before choosing a company.
Final Takeaway: Know What's Underneath Your Split
You don't need to become obsessed with your Schedule A.
You do need to understand it.
A transaction cost of six cents instead of four cents may sound meaningless until the merchant processes 5,000 transactions and that two-cent difference becomes $100 every month.
A $5 statement-fee difference can become $500 across 100 merchants.
A BIN or sponsor fee that looks small on one account can become meaningful across an established portfolio.
A monthly fee you casually waive for the merchant can still cost you money if the underlying Schedule A expense remains.
None of those costs automatically makes a program bad.
The important thing is knowing they're there.
My first Schedule A had a transaction cost around ten cents, and I didn't even realize how much that could affect the profitability of my accounts.
I learned later.
You don't have to.
Understand the major costs.
Understand your residual split.
Understand how the two work together.
Then get back to what actually builds the portfolio:
Selling merchants.
About Joe Wagner
Joe Wagner has spent more than 16 years in merchant services and payment-processing sales, acquiring merchants, building recurring-revenue portfolios and developing sales organizations.
His focus today is helping agents understand the business underneath the sales pitch so they can make better decisions about compensation, agreements and merchant-services partners.
If you're still building your foundation, learn how merchant services agents get paid, review how to choose a merchant services agent program, and understand the 11 questions to ask before signing a merchant services agent agreement.
You can also browse the Merchant Sales Training Blog, explore Merchant Sales Resources, or begin learning free through Merchant Service University.
Free education. No obligation. Get educated before you get recruited.