How to Compare Merchant Services Companies Without Getting Sold
How to Compare Merchant Services Companies Without Getting Sold
If you're trying to compare merchant services companies, stop looking for someone to tell you which company is universally the best.
There probably isn't one.
One merchant-services company may be an excellent fit for an experienced salesperson who wants substantial upfront commissions. Another may make more sense for someone focused primarily on building a long-term residual portfolio. Another may have technology, underwriting or merchant support that better fits the types of businesses you plan to pursue.
This is why I don't believe the right question is:
"What's the best merchant services company?"
The better question is:
"Which merchant services company is the best fit for what I'm trying to build?"
That's also the philosophy behind how I work with sales agents today.
I have relationships with multiple merchant-services companies because different agents have different priorities. The partners I work with all have residual structures I consider competitive, but they are not identical. One partner can pay up to $10,000 upfront on certain qualified merchant accounts based on profitability and program requirements. Other partners may not emphasize massive upfront payouts but offer other advantages that could matter much more to a particular salesperson.
Before I recommend anything, however, I would rather help someone understand the industry.
That's why I created Merchant Service University.
Learn first. Figure out what matters to you. Then compare companies.
That keeps you from choosing a long-term business partner based entirely on whichever recruiter gives the best presentation.
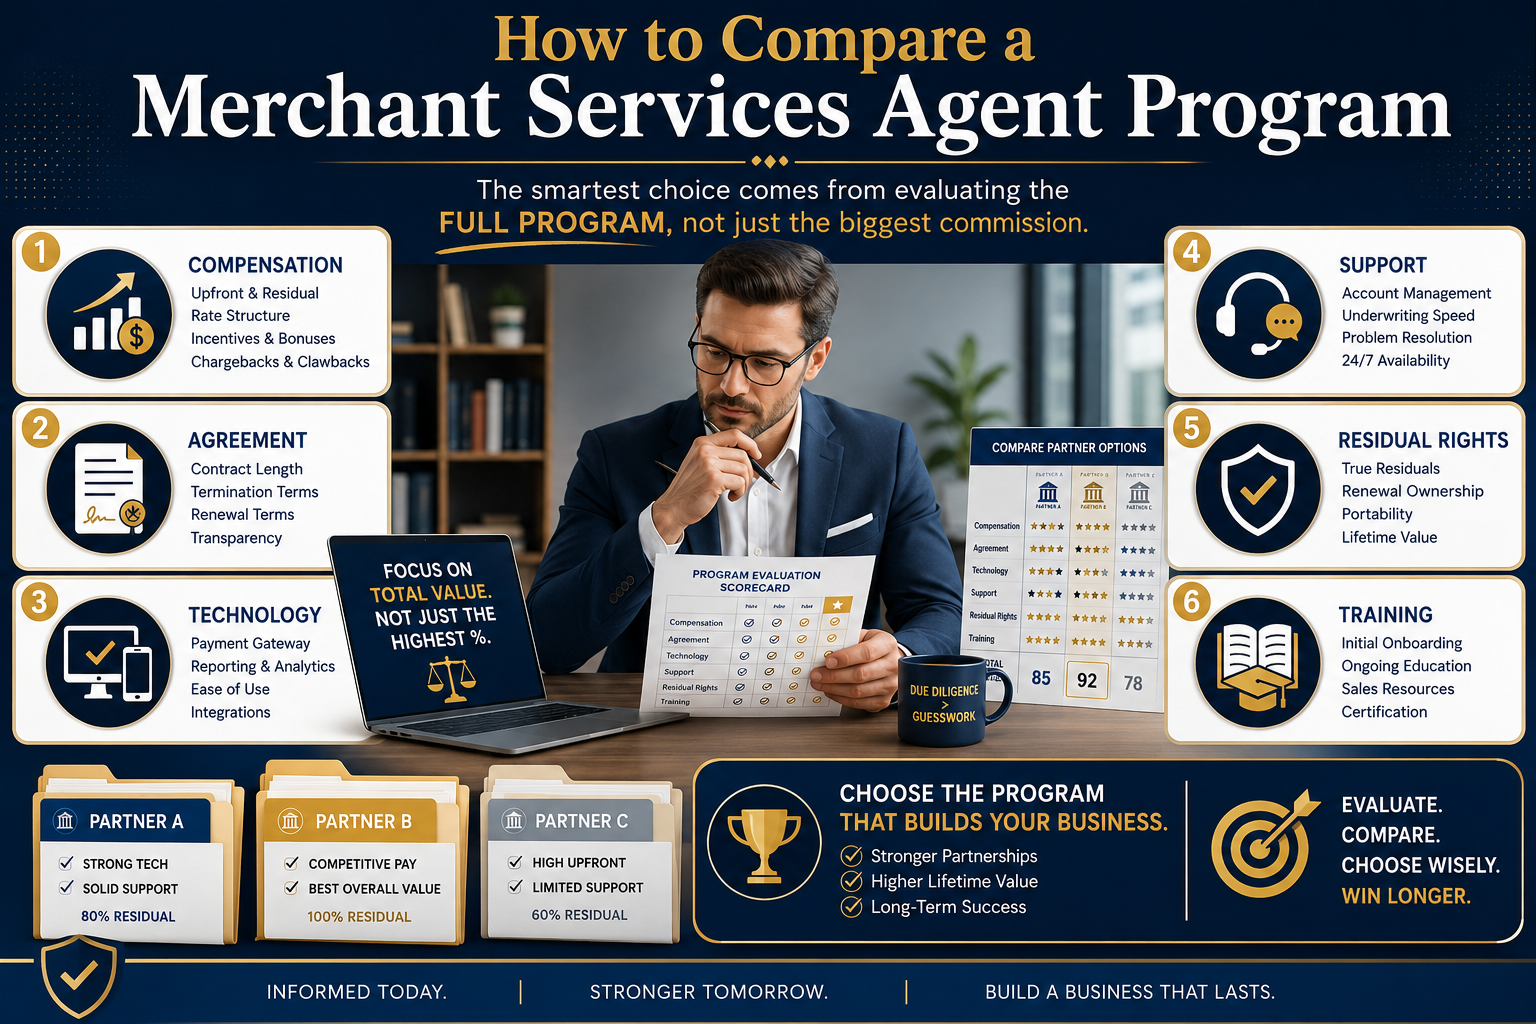
Start by Defining What You Actually Want
Before comparing companies, define your own priorities.
This sounds simple, but most agents skip it.
Suppose you're an experienced salesperson transitioning from another commission-driven industry. You already know how to close, but you need meaningful cash flow while your residual portfolio develops. Upfront compensation may be extremely important to you.
Another salesperson may have stable income elsewhere and be entering merchant services specifically because they want to build recurring income over the next ten years. That person may care much more about vesting, residual rights, Schedule A economics and merchant retention.
Another agent may already have relationships in restaurants, salons, professional services or another particular vertical. For that person, the technology and underwriting capabilities of the partner may be more important than another five percentage points of compensation.
These agents shouldn't automatically choose the same company.
So before evaluating any program, ask yourself:
What am I trying to build?
That question should drive everything that follows.
1. Compare the Real Residual Economics, Not Just the Percentage
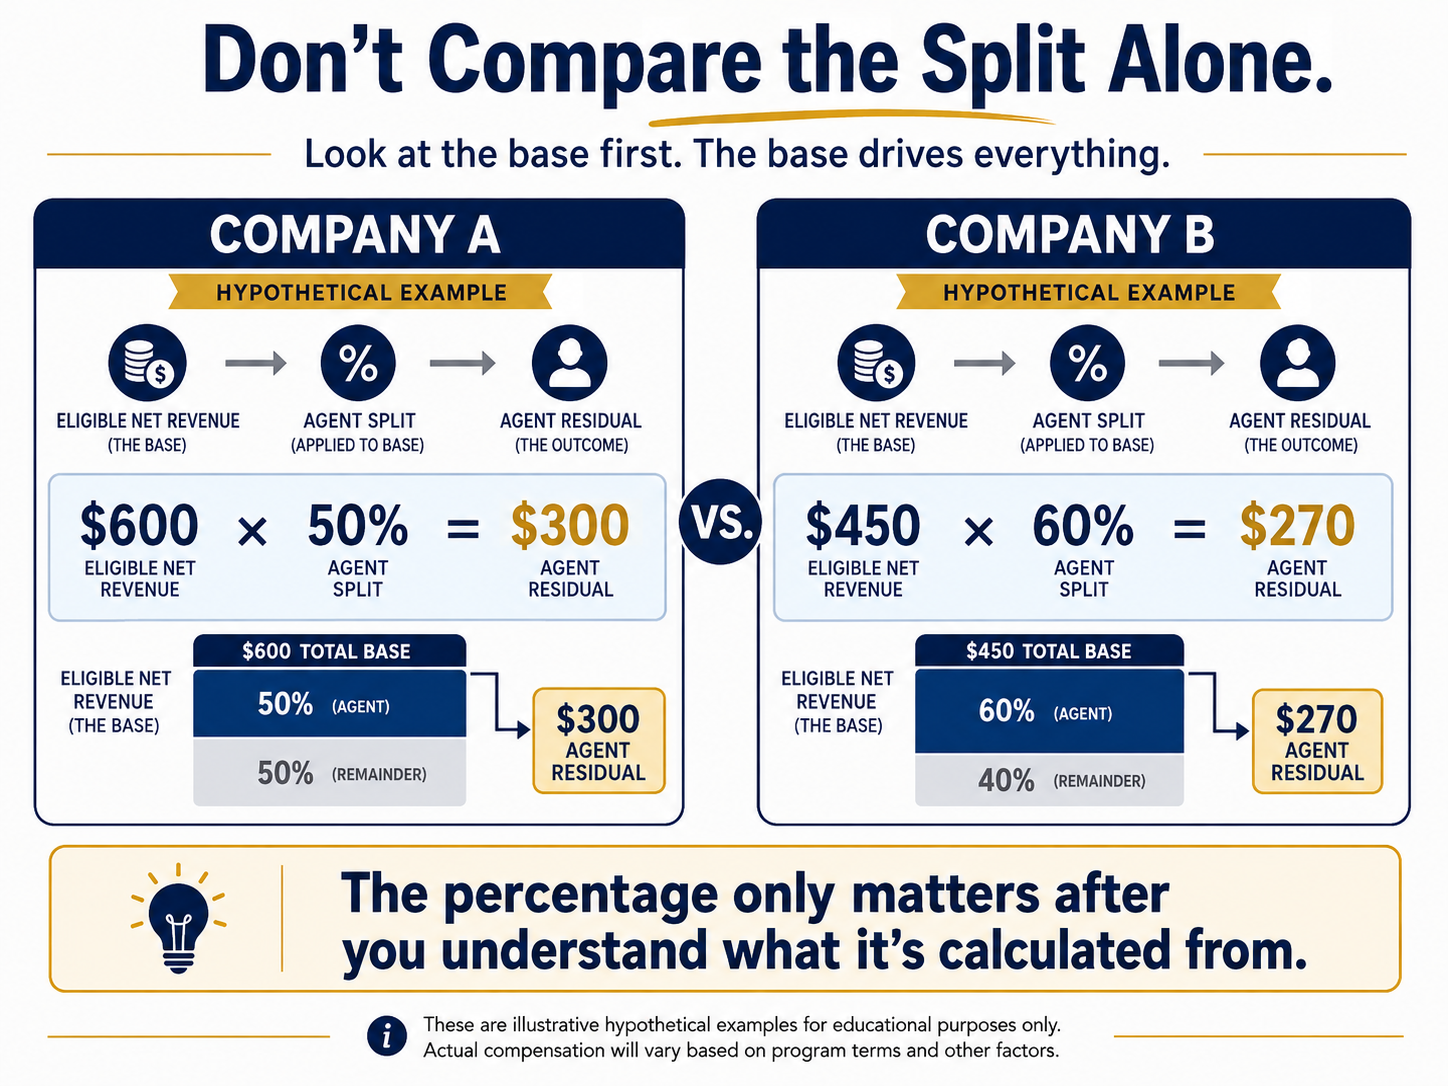
Residual split is obviously important.
I generally like working around a clean 50% residual split, with opportunities in some structures to reach 55% or 60% depending on production and the relationship.
But we've already established throughout this series that the percentage alone doesn't tell you what you'll actually earn.
A company offering 60% can still produce less residual income than a company offering 50% if its underlying costs leave less profit available to divide.
That's why you need to understand the major costs underneath the residual.
You don't need to compare twenty-seven individual Schedule A line items and become a payment-processing accountant.
Keep it practical.
What is the transaction cost?
What are the meaningful monthly costs?
Are there statement fees?
BIN or sponsorship-related fees?
Monthly minimums?
Are there other significant expenses that will affect the merchants you intend to sell?
A two-cent transaction-cost difference can become $100 per month on a merchant running 5,000 transactions. Across a portfolio, small differences multiply.
I walk through these examples in Merchant Services Schedule A Explained.
Then read Merchant Services Residual Splits Explained so you understand how the Schedule A and residual percentage work together.
The goal isn't finding zero costs.
Every organization has costs.
The goal is making sure the economics are reasonable and understandable.
2. Compare Upfront Compensation Based on Your Cash-Flow Goals
This is one of the biggest areas where merchant-services programs can differ.
Some agents barely care about upfront commissions.
Others should care a lot.
If you're an experienced producer who can bring in large, profitable merchants, strong upfront compensation can fundamentally change the cash flow of the opportunity.
As I mentioned earlier, one partner I work with can pay up to $10,000 upfront on certain qualified deals based on merchant profitability and program terms.
That doesn't mean every merchant pays $10,000.
It isn't guaranteed income.
The account has to qualify, and the economics of the merchant determine what is available.
But for the right salesperson, that type of program can be extremely attractive.
Now compare that with an agent whose number-one goal is creating a long-term recurring portfolio. That person may willingly accept a different upfront-compensation structure because another partner offers benefits more closely aligned with that goal.
This is why I explained in Upfront Commissions vs. Residual Income in Merchant Services that neither compensation model is automatically superior.
You're comparing the compensation plan against your objectives.
3. Compare the Agent Agreement Before the Recruiting Pitch
This might be more important than the compensation.
The recruiter eventually goes away.
The agreement remains.
Before committing years of production to an organization, understand what happens to the merchants and residual income you're building.
When do residuals vest?
What happens if you stop producing?
What happens if you voluntarily leave?
What happens if the company terminates your agreement?
Are there production minimums?
Can compensation be changed?
What happens if the company is acquired?
What restrictions apply after the relationship ends?
A company can offer excellent products and attractive compensation while still having contract provisions you aren't comfortable accepting.
That doesn't automatically make it a bad company.
It means you need to understand the relationship you're entering.
My guide to the 11 Questions to Ask Before Signing a Merchant Services Agent Agreement walks through those issues, and Merchant Services Contract Red Flags explains the areas where I would slow down and ask for additional clarification.
If the agreement will control years of recurring compensation, take it seriously.
4. Compare Residual Rights, Not Just Residual Rates
This deserves its own category.
Suppose Company A gives you 50% with clearly defined vesting and strong continuing residual rights.
Company B gives you 60%, but the agreement contains continuing production requirements that could affect existing residual payments if you stop selling.
Which one is better?
There isn't enough information to answer that question from the percentages alone.
For me, residual rights carry enormous weight.
I don't want to spend ten years building a merchant portfolio without understanding whether my contractual right to that income continues if my life or business changes.
This is why the phrase lifetime residuals should trigger questions rather than excitement alone.
Does "lifetime" mean as long as the merchant continues processing?
Does it survive your departure?
Are there conditions?
What happens after a sale of the ISO?
What happens if you retire?
What happens at death?
I've covered those questions in What Lifetime Residuals Really Mean in Merchant Services.
A higher residual percentage cannot compensate for rights you don't understand.
5. Compare Merchant Support Like It Is Part of Your Compensation
Merchant support doesn't appear as a percentage on a compensation plan.
I still consider it part of compensation.
Why?
Because if the merchant leaves, your residual becomes zero.
Suppose Company A gives you 60% but your merchants consistently struggle to reach support, equipment problems take too long to resolve and onboarding creates unnecessary frustration.
Company B gives you 50% but its merchants receive excellent support and remain happy.
Which portfolio would you rather own five years from now?
Retention matters.
I've personally had to step into merchant situations simply to keep deals alive because problems after the sale created unnecessary frustration. Experiences like that taught me that the sale is not finished when the application is approved.
You need to know who takes care of the merchant afterward.
Ask:
Who does the merchant call?
Can you reach someone when a serious issue occurs?
How are equipment problems handled?
How strong is technical support?
How quickly are merchant problems escalated?
Will you have someone internally who actually knows your accounts?
If your business model depends on recurring residuals, backend support is protecting the asset you're trying to build.
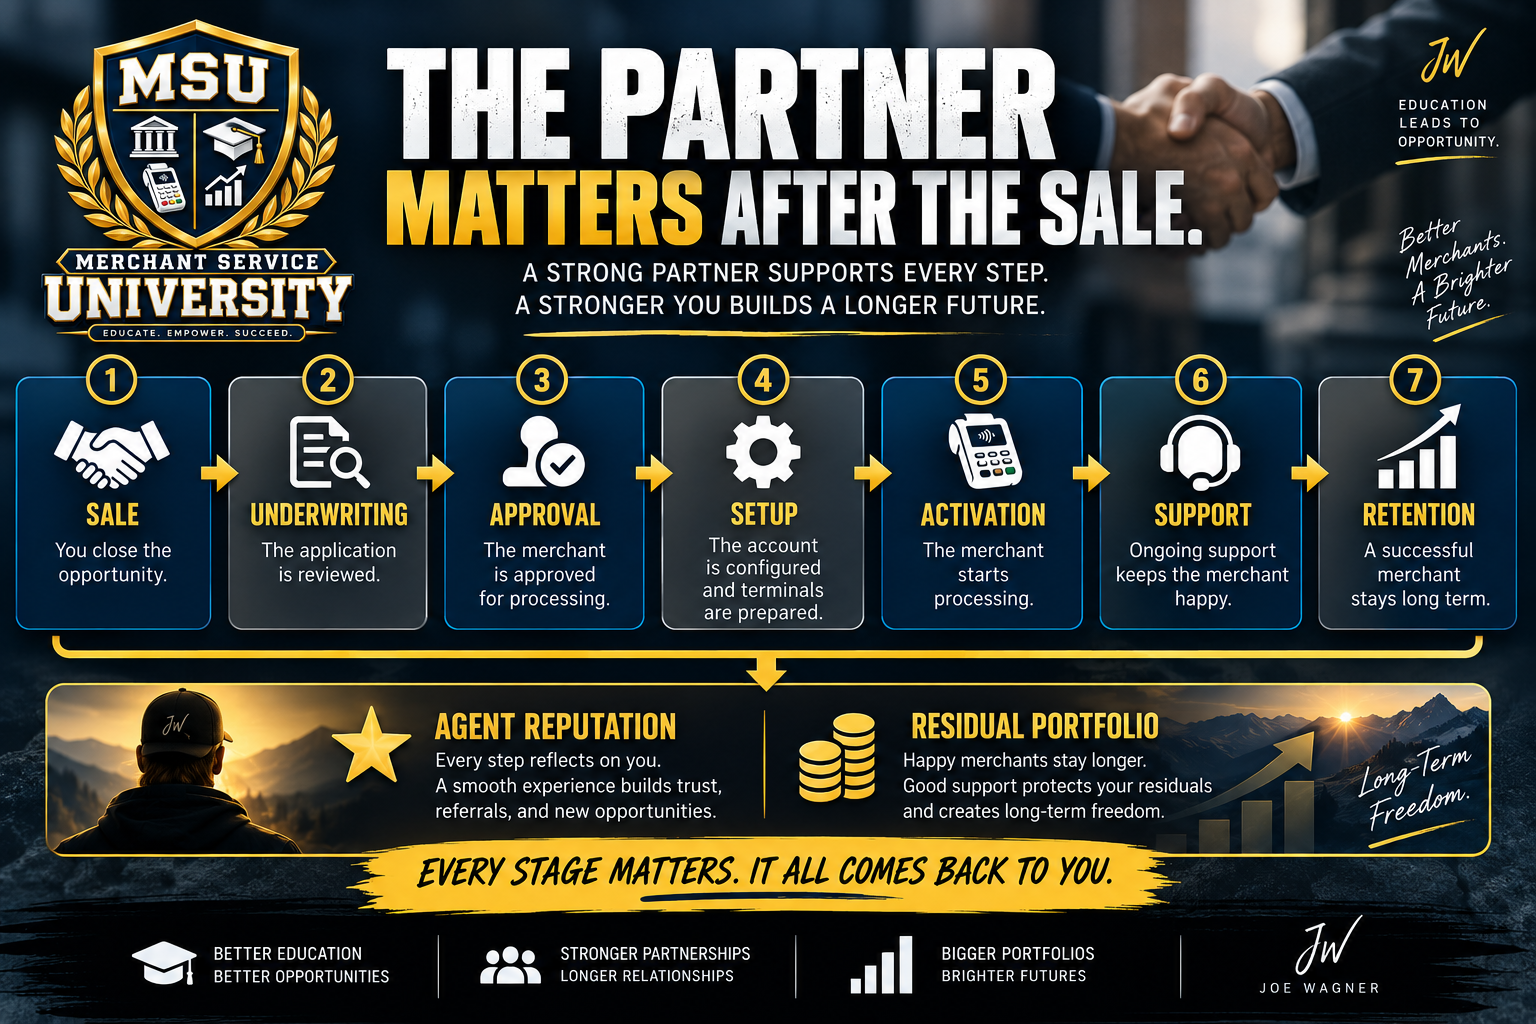
6. Compare Underwriting and Onboarding
This is another factor new agents overlook because they haven't sold enough accounts yet to know how painful bad onboarding can become.
Selling the merchant is only the beginning.
The account then has to make it through underwriting.
Documentation may be required.
The business may need verification.
Hardware or software must be configured.
The account needs to activate.
Funding needs to work.
When that process is smooth, the salesperson looks good.
When that process becomes unnecessarily complicated, the salesperson is the person standing in front of the merchant trying to explain what is happening.
Different processors and ISOs may also have different underwriting appetites.
One partner might fit straightforward retail and service merchants extremely well.
Another may have more flexibility for certain business types.
Another may have technology better suited for a particular vertical.
This matters if you already know which merchants you plan to pursue.
The company needs to fit your market.
7. Compare What You Can Actually Sell
Merchant services isn't just countertop credit-card terminals anymore.
Businesses increasingly expect commerce technology.
Depending on the merchant, that can include point-of-sale systems, invoicing, e-commerce, appointments, inventory, customer management, online ordering, employee tools, loyalty and other software.
But not every merchant needs everything.
Sometimes the best solution really is a simple terminal.
That's why I want a partner that gives me enough flexibility to solve the merchant's problem rather than forcing the exact same product into every business.
If your target market is restaurants, understand the restaurant technology.
If you're selling salons, understand appointment functionality.
If you're calling contractors, understand invoicing and mobile payments.
If you're pursuing traditional retail, understand inventory and point of sale.
Don't ask only:
"What processor does this company use?"
Ask:
"What can I actually put in front of the merchants I'm going to sell?"
The best economics in the world won't help if the product doesn't fit your market.
8. Compare Reporting and Transparency
If you're building residual income, you should have a reasonable way to understand what you're being paid.
Can you see merchant-level residual data?
Can you identify which accounts generated income?
Can you understand deductions?
Can someone explain the calculation when you have a question?
If you have 100 merchants, you shouldn't have to blindly trust that a number appearing in your bank account is correct without any meaningful supporting information.
Transparency builds trust.
You don't need a dashboard containing every piece of data ever generated by the processing system.
You do need enough information to understand your own portfolio.
9. Compare the People, Not Just the Company Logo
This one is harder to put on a spreadsheet, but I think it matters tremendously.
Who will actually support you?
Who answers when you have a difficult merchant?
Who helps you understand underwriting?
Who can help structure a large deal?
Who helps when you get stuck?
Is there training after onboarding?
Can you speak with experienced people?
A large company can have great technology and still give an individual agent a poor experience if that agent doesn't have access to the right people.
A smaller organization can have incredible personal support but lack products or infrastructure you need.
Again, there is no universal answer.
Evaluate the actual relationship you're entering.
10. Compare the Opportunity Based on Your Business Model
This is where everything comes together.
Imagine three salespeople.
The first is a high-ticket closer with access to large merchants and wants significant cash flow today.
The second wants to spend the next decade building hundreds of merchants and cares deeply about residual rights and retention.
The third already works with a specific type of business and needs the best technology and underwriting for that vertical.
If I sent all three to the same company simply because that company paid me the most to recruit them, I wouldn't be doing my job very well.
I would rather understand the salesperson first.
Then evaluate the tools.
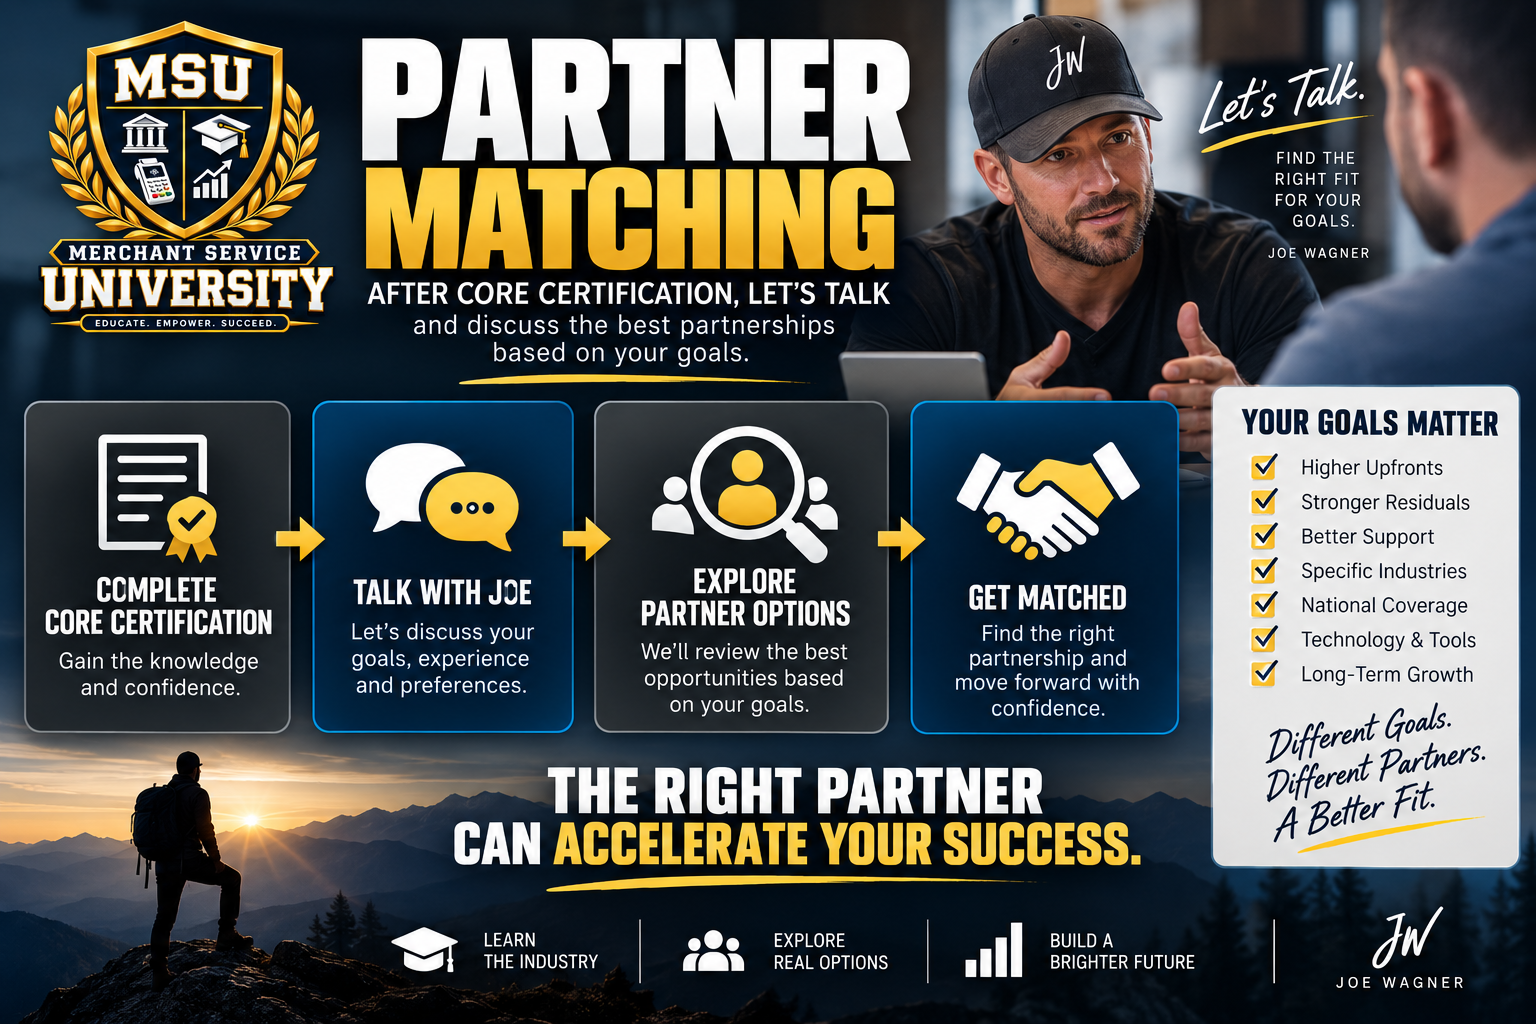
That is the basis of my partner-matching approach.
The Simple Merchant Services Company Scorecard
You do not need to create a 100-line spreadsheet.
Keep your comparison simple.
Factor | What You Need to Understand |
|---|---|
Residual Economics | Is the split competitive and are the major underlying costs reasonable? |
Upfront Compensation | Does the program match your immediate cash-flow goals? |
Residual Rights | What happens if you stop producing, leave or retire? |
Agreement | Are the obligations, restrictions and termination provisions understandable? |
Technology | Can you solve the problems faced by your target merchants? |
Underwriting | Can the partner effectively board the types of businesses you pursue? |
Merchant Support | Will the backend experience help you retain accounts? |
Reporting | Can you understand how your residual compensation is calculated? |
Agent Support | Can you get help closing, onboarding and solving problems? |
Overall Fit | Does the relationship match the business you actually want to build? |
I care far more about these ten answers than someone claiming to have the #1 agent program in America.
Don't Compare Companies Before You Understand the Terminology
This is the mistake I want to help new agents avoid.
If you've never heard the terms Schedule A, vesting, residual split, BIN fee, clawback or merchant attrition, you're not really ready to compare processing companies yet.
You're trying to compare things you don't understand.
That's where Merchant Service University comes in.
The core training is free.
There is no obligation to join one specific processing company.
Learn how the industry works first.
Understand compensation.
Understand pricing.
Understand agreements.
Understand technology.
Understand the merchant sales process.
Then your company comparison becomes much easier.
As I explain in Merchant Services Training for Beginners, education changes the conversation from:
"Tell me whether this opportunity is good."
to:
"Does this opportunity fit what I'm trying to accomplish?"
That's where I want you.
Already Experienced? I Can Help You Think Through Partner Options
You may already be selling merchant services.
Maybe you've been doing it for years.
In that case, you may not need beginner education.
Maybe you're here because you're wondering whether your existing program still makes sense.
You might have good residuals but poor support.
Great support but weak technology.
Good economics but almost no upfront compensation.
Strong upfront money but contract terms you don't love.
Or maybe your existing relationship is great and there's no reason to move at all.
That's an acceptable answer too.
My goal isn't convincing someone to switch companies unnecessarily.
My role is to help you understand what options may exist and which partner structure fits what you're trying to build.
If you want that conversation, you can reach out through JoeWagner.com.
Tell me what's most important to you.
We can start there.
Why I Work With Multiple Merchant Services Partners
This is really the conclusion of the entire article.
If I believed one company was the best answer for every salesperson, I wouldn't need multiple relationships.
But that's not how this industry works.
Different companies have different strengths.
I work with partner relationships that I believe offer good residual economics, while allowing me to look at other variables that may matter more to the specific agent.
One partner may make sense because of substantial upfront compensation.
Another may offer advantages in technology.
Another may make more sense based on underwriting, support or the agent's long-term portfolio strategy.
That gives me the ability to begin with the salesperson rather than the processor.
What do you want to build?
Once I understand that, I can give you much better suggestions.
Frequently Asked Questions About Comparing Merchant Services Companies
How do I compare merchant services companies as a sales agent?
Compare residual economics, major Schedule A costs, upfront compensation, residual rights, agent agreement terms, technology, underwriting, merchant support, reporting and the actual support available to you as an agent.
What is the best merchant services company for agents?
There is no single company that is automatically best for every agent. The right fit depends on priorities such as upfront compensation, recurring residual income, technology, underwriting, support and the types of merchants the salesperson plans to pursue.
Is the highest residual split always the best merchant services program?
No. A higher residual percentage can still generate less actual compensation if the underlying costs leave less eligible profit to divide. Residual rights and merchant retention also matter.
Is a 50% merchant services residual split competitive?
A clean 50% residual arrangement can be very strong when the underlying costs are reasonable, reporting is transparent and the agent has appropriate contractual residual rights.
Should I choose a merchant services company based on upfront commissions?
Upfront compensation should be considered if immediate cash flow is important, but it should be evaluated alongside residual income, contract terms, merchant support and potential clawback provisions.
Can merchant-services agents earn large upfront commissions?
Some programs offer substantial upfront compensation on qualified merchants. One partner Joe Wagner works with can pay up to $10,000 on certain qualified deals based on profitability and program requirements. This is not guaranteed compensation and does not apply to every merchant.
How important is merchant support when comparing processors?
Very important for a residual-focused agent. Poor merchant support can contribute to attrition, and a merchant that leaves no longer contributes ongoing residual income.
Why does underwriting matter to a sales agent?
Different processing organizations can have different underwriting requirements and appetites. A partner should be capable of effectively boarding the types of merchants an agent plans to pursue.
Should I compare every Schedule A fee between companies?
You should understand the meaningful costs affecting your expected merchants, but a new agent does not necessarily need to build an exhaustive line-by-line comparison. The goal is to understand whether the underlying economics are reasonable and how they affect actual residual payouts.
Should I learn merchant services before comparing companies?
Yes. Understanding processing, residuals, Schedule A economics, agreements and merchant technology makes it much easier to compare companies intelligently.
Can Joe Wagner help me compare merchant services partners?
Yes. Joe works with multiple merchant-services partner relationships and helps agents evaluate potential fits based on what they are trying to build rather than automatically recommending the same company to everyone.
Is Merchant Service University tied to one processor?
No. The core Merchant Service University education is free and does not obligate students to join one specific merchant-services company.
Final Takeaway: Stop Looking for "The Best Company"
There is a better question.
What's the best company for you?
A salesperson who needs significant upfront cash flow may need something different from the agent building a ten-year residual portfolio.
An agent targeting restaurants may need something different from someone selling professional services.
Someone who already knows how to close may value a different support structure from a brand-new salesperson.
That's why comparing merchant-services companies should begin with your goals.
Understand the real residual economics.
Understand the agreement.
Understand the residual rights.
Look at the upfront compensation.
Evaluate the technology.
Evaluate underwriting.
Find out who supports your merchants.
Find out who supports you.
Then decide.
If you're brand new, start by getting educated through Merchant Service University. The core education is free and there is no obligation to join one specific company.
If you're already experienced and want to talk through what matters most to you, reach out to me through JoeWagner.com.
I work with multiple partner relationships specifically because I don't believe every salesperson belongs in the same program.
The company is a tool.
Your merchant portfolio is the business you're building.
Learn enough to choose the right tool.
About Joe Wagner
Joe Wagner has spent more than 16 years in merchant services and payment-processing sales, acquiring merchants, building recurring-revenue portfolios and developing sales organizations.
He created Merchant Service University to give sales agents foundational merchant-services education before requiring them to choose a processing partner.
Joe also works with new and experienced merchant-services representatives to evaluate potential partner relationships based on residual economics, upfront compensation, technology, underwriting, support and long-term portfolio goals.
Continue your research with How to Choose a Merchant Services Agent Program, Merchant Services Schedule A Explained, Merchant Services Residual Splits Explained, What Lifetime Residuals Really Mean, Merchant Services Contract Red Flags, and Merchant Services Training for Beginners.
Or begin your core education free at MerchantServiceUniversity.com.